Market News
Stocks to watch today: chips bounce, Cloudflare and Airbnb surge — but the jobs report decides it
After the Nasdaq's worst day since April 2025, futures point to a tech rebound — Nvidia, AMD and Micron are all higher premarket, and Cloudflare and Airbnb are surging on earnings. Everything hinges on the 08:30 ET jobs report.
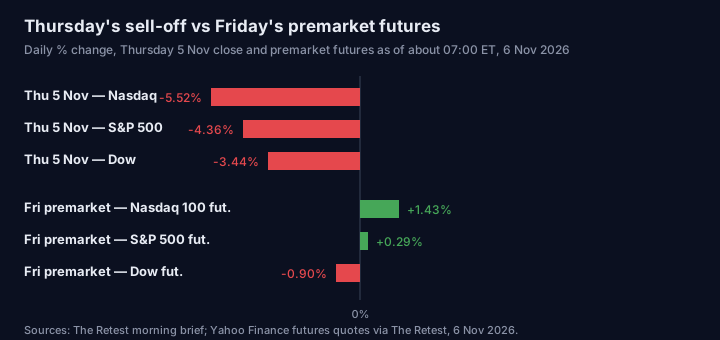
Friday 6 November opens with the market trying to stand back up. Thursday was a rout: the Dow fell 1,833 points, or 3.44%, to 51,523.06; the S&P 500 dropped 4.36%; and the Nasdaq Composite fell about 5.5%, its worst day since April 2025, closing in correction territory. The Nasdaq 100 lost 6.36% and the PHLX Semiconductor Index sank 12.25% to 9,011.14. The VIX closed at 26.07 after its biggest one-day jump in about 19 months.
This morning the bounce is real but narrow. As of about 07:00 ET, Nasdaq 100 futures were up about 1.4% to 1.6%, S&P 500 futures were up about 0.2% to 0.4%, and Dow futures were down about 0.6% to 1.0%. Technology is rebounding; the Dow is not joining in. And nothing is settled: the October jobs report lands at 08:30 ET, one hour before the open, and it will set the tone for the whole session.
The jobs report: the day's main event
The October nonfarm payrolls report is due at 08:30 ET. A Reuters poll expects payrolls of about 65,000, an unemployment rate of 4.2% and average hourly earnings up 0.3% for the month. September added only 29,000 jobs.
Why it matters: traders still price a better-than-65% chance that the Federal Reserve raises rates in December, according to the CME FedWatch Tool as reported by Reuters. A hot payroll print or faster wage growth would reinforce the case for higher rates and could reignite Thursday's sell-off. A soft reading would give the rebound room to run. Preliminary Michigan consumer sentiment follows at 10:00 ET.
Chips: the rebound leaders
Nvidia (NVDA) — up about 3.6% to 3.9% premarket, after closing Thursday at $181.60, down 9.26% — its biggest one-day fall since January 2025, according to Reuters. Watch whether it holds the bounce once regular-hours trading starts; Thursday's low will be the first test if selling resumes.
AMD — up about 7.6% to 8% premarket, and Micron (MU) — up about 8.3% to 8.8%. Memory is leading the chip rebound: SanDisk jumped more than 10% to 12% premarket, and Marvell rose about 8.2%, Broadcom about 5.1%, Intel about 4.9% and TSMC about 6.3%. The whole semiconductor complex sold off together on Thursday; today it is recovering together. The question is whether this is bargain hunting or a durable turn — the jobs report will help decide.
Cloudflare (NET): the earnings star
Cloudflare surged about 19% to 20% premarket, to around $291.62. Third-quarter revenue grew 39% year over year to $782.5 million and adjusted earnings per share reached $0.38, both topping market expectations, and the company raised its full-year guidance. It is the clearest proof in this earnings season that not every software story was caught in the AI spending scare. Watch whether the gain holds through the open — premarket pops on earnings often fade in the first hour.
AppLovin (APP): yesterday's winner, still in focus
AppLovin rose 31.04% on Thursday, the day's standout, after third-quarter revenue of $2.18 billion grew 55.5% and fourth-quarter revenue guidance of $2.38 billion came in above the $2.25 billion estimate. Net income rose 72% to $1.44 billion. It closed at $356.10, adding about $25.8 billion in market value in a day on volume four times its average. After a move that big, watch whether it consolidates or gives some of it back — and whether the rest of the ad-tech group follows.
Moderna (MRNA): beat and a raised outlook
Moderna bounced back in premarket trading after a 6.55% drop on Thursday to $241.46. Third-quarter revenue was $1.3 billion, up about 29% year over year and beating consensus by $409.8 million, driven by stronger COVID vaccine sales in overseas markets. Net income was $162 million, against a $200 million loss a year earlier, and the company raised its full-year revenue growth outlook to 15%–25%, up from up to 10% previously. Watch whether the healthcare sector joins the rebound — it was the worst-performing sector in premarket trading, down 1.4%, despite the Moderna beat.
Airbnb (ABNB): fastest growth in three years
Airbnb rose about 12% premarket to around $190, after closing Thursday at $170.13, down 3.54%. Third-quarter earnings per share were $3.16, beating the $2.85 estimate, and revenue rose 19% to $4.87 billion, ahead of the $4.75 billion consensus — its fastest growth in over three years. The company also raised its 2026 outlook, guided fourth-quarter revenue of $3.22 billion to $3.28 billion, and approved a new $12 billion share buyback. Watch whether travel and consumer names follow it higher, or whether the gain stays isolated.
DraftKings (DKNG): the earnings warning
DraftKings fell about 21% premarket after an earnings miss and a cut to EBITDA guidance, blamed on heavy investment in prediction markets. It is the day's clearest reminder that guidance cuts are being punished far harder than beats are being rewarded. Watch whether the selling spreads to other consumer and gambling names, or stays contained to DraftKings.
IREN: the AI-cloud rebound
IREN jumped about 17% to 19% premarket after fiscal first-quarter results showed AI cloud revenue nearly tripling to $200 million, from $71 million in the previous quarter and ahead of the $185 million consensus. Total revenue rose to $228 million and the net loss narrowed to $263 million from $684 million. The stock had plunged more than 55% over the past month, including a 17% fall on Thursday alone. Goldman Sachs kept a Neutral rating with a $30 price target; BTIG kept a Buy but cut its target to $65 from $80. Watch whether the neocloud group — Cipher Mining, CoreWeave and Nebius were all up premarket too — holds its gains after the open.
Vistra (VST): earnings due today
Vistra reports third-quarter results today, with its earnings call later in the session. Full-year adjusted EBITDA guidance stands at $6.8 billion to $7.6 billion, excluding the Cogentrix acquisition closed on 30 October and the Meta contract. Vistra fell 6.15% on Thursday alongside fellow AI-power names Oklo (down 13.20%) and TeraWulf (down 13.85%), which also report today. Watch whether Vistra's guidance changes the AI-power story — it is the next test of whether the data-centre spending scare has further to run.
The overall picture
The premarket message is a split one: a sharp tech and chip rebound, led by earnings winners, while the Dow lags and healthcare and financials stay soft. Gold futures were down about 0.8% to 0.9%, near $4,075–$4,080, and crude oil rebounded to about $100 a barrel. The bounce is a relief move off an oversold market, not yet a conviction reversal — and the jobs report at 08:30 ET decides which way the day goes.
For exploration only. Not financial advice.
Sources
- The Retest: Morning Brief, Friday, November 6, 2026
- Frenzy Capital: Stock Market Analysis for Friday, November 6, 2026
- TradingKey via Mitrade: Chip Stocks Rebound as Micron, AMD Rise Over 8%
- Hollow Point Trading: Overnight — Nasdaq Bounces, Breadth Is Broken, and Payrolls Comes Next
- Upstox: Dow futures hint negative open, S&P 500, Nasdaq futures trade higher on Nov 6
- KuCoin News: Pre-market AI and tech stocks rally; MU and SanDisk surge over 8%
- The Stock Market Watch: Premarket Movers, November 6, 2026
- MEXC Crypto Pulse: Pre-Market Briefing on Nov 6
- Invezz: Why is IREN stock surging more than 17% during premarket trading on Friday?
- Seeking Alpha: Moderna stock rises on Q3 beat, guidance hike
- CoinCentral: Airbnb (ABNB) Stock Jumps After Fastest Revenue Growth in Three Years
- Finnhub: Moderna (MRNA) and Airbnb (ABNB) market data, November 6, 2026