Market News
Midday: the Nasdaq leads a fragile rebound after a hot jobs report — but the bounce is already fading
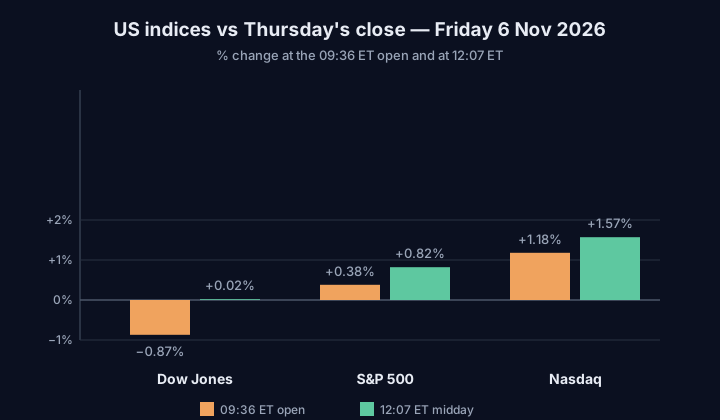
As of about 12:07 ET the Nasdaq is up 1.6% and the S&P 500 up 0.8% after Thursday's rout, while the Dow is flat. A much stronger-than-expected jobs report has lifted December rate-hike bets above 76% — and the morning's big winners have already given back about half their premarket gains.
Friday 6 November, midday: the market is trying to recover from its worst day since April 2025, and so far the recovery is real but thin. As of about 12:07 ET, the Nasdaq Composite is up 1.57% at 24,695.67, the S&P 500 is up 0.82% at 7,414.06 and the Dow Jones Industrial Average is essentially flat, up 0.02% at 51,531.72. The Russell 2000 is up about 0.89%. The fear gauge is easing — the VIX is down 13.8% to 24.27 — but it is still far above Wednesday's close of 16.61.
Thursday's damage is the starting point. The Dow closed down 1,833.06 points, or 3.44%, at 51,523.06; the S&P 500 fell 4.36% to 7,353.73; and the Nasdaq fell 5.52% to 24,315.00, more than 10% below its record closing high of 27,599.89 set on 6 October — in correction territory. The sell-off wiped out around $2.3 trillion in market value in a day. Through Thursday, the Nasdaq was down about 4.4% for the week and the S&P 500 about 3%.
Figures in this article are intraday snapshots captured in New York between the open and about 12:07 ET. The session had not closed when this was written.
The jobs report: strong hiring, higher rate-hike bets
The day's main event landed before the open. The October nonfarm payrolls report, released at 08:30 ET, showed the economy added 165,000 jobs — nearly triple the roughly 59,000 to 65,000 economists expected. The unemployment rate slipped to 4.1% from 4.2%, and average hourly earnings rose 0.4% for the month to $38.00, with annual wage growth accelerating to 3.1% from 3.0%. September's payroll gain was revised up to 60,000 from 29,000, and August's to 186,000 — 84,000 extra jobs added to the two previously reported months.
Good news for the economy, awkward news for the market. A hot labour market strengthens the case for the Federal Reserve to raise rates at its 8–9 December meeting, and traders now price a better-than-76% chance of a December hike, according to the CME FedWatch Tool. The 10-year Treasury yield rose to about 4.864% in the morning and stood at 4.849% at 12:07 ET. That is the split running through the whole session: strong jobs support earnings, but higher-for-longer rates punish the expensive growth stocks that led Thursday's fall.
A second data point helped the mood at 10:00 ET. The University of Michigan's preliminary November consumer sentiment index rose to 51.0 from 48.0 in October, beating expectations of no change, and one-year inflation expectations cooled to 4.3% from 4.7%. Households feeling a little better, and expecting a little less inflation, is exactly the combination a nervous market wants to see.
The morning's trajectory: a split open that slowly broadened
The open was split down the middle. At 09:36 ET the Nasdaq was up 1.18% at 24,601.93 and the S&P 500 up 0.38% at 7,381.99, while the Dow fell 449.65 points, or 0.87%, to 51,073.41. Chips and tech bounced; the Dow's rate-sensitive and value names did not.
The bounce then broadened. By 10:01 ET the Nasdaq was up 1.7% at 24,732.09, the S&P 500 up 0.9% at 7,421.33 and the Dow had pared most of its loss to down 0.2% at 51,395.68. By 11:01 ET the Dow had turned positive, up 0.11% at 51,579.73, with the Nasdaq up 1.53% and the S&P 500 up 0.87%. At 11:42 ET the Nasdaq stood at 24,740.91, up 1.75%, its best level of the morning, with the VIX down 15.3% to 23.85.
Since then the market has plateaued rather than pushed higher. By 12:07 ET the Nasdaq had eased to up 1.57% and the S&P 500 to up 0.82%, while the Dow slipped back to flat. The rebound is holding, not extending.
What is leading, and what is lagging
Chips are leading, but the gains are fading from their premarket highs — and that is the most important detail of the morning.
AMD is up 7.88% at $436.26, after closing Thursday at $404.40. It opened at $444.43 and touched $459.80 in the morning before drifting back. Even after today's bounce, AMD is down about 23% over the past five sessions.
Micron (MU) is up 4.50% at $685.95, after closing at $656.39. It was up more than 8% premarket and opened at $708.35, touching $724.80, before giving back roughly half the gain. Micron is down about 26.6% over the past five sessions.
Nvidia (NVDA) is up 2.40% at $185.96, after closing at $181.60. It opened at $191.10 and reached $194.90 before fading. Nvidia is down about 13% over the past five sessions.
Cloudflare (NET) is the earnings star, up 10.94% at $271.26 after closing at $244.51 — but it was up 19% to 20% premarket, opened at $286.97 and has not been back to that level since. Third-quarter revenue grew 39% year over year to $782.5 million and adjusted earnings per share reached $0.38, both topping expectations, and the company raised its full-year guidance. The market is rewarding the beat, just less generously than the premarket suggested.
The pattern is consistent: the morning's winners opened strong and then gave back roughly half their premarket gains. That is bargain hunting, not conviction. Buyers are willing to step in at Thursday's prices, but not to chase.
Elsewhere, Airbnb (ABNB) was up about 12% premarket after third-quarter revenue rose 19% to $4.87 billion — its fastest growth in over three years — and the company approved a new $12 billion buyback. IREN was up about 18% premarket after AI cloud revenue nearly tripled to $200 million. DraftKings (DKNG) is the day's warning: it was down 21% to 27% premarket after third-quarter revenue of about $1.33 billion missed the $1.39 billion estimate and it cut its full-year EBITDA outlook to $225 million, far below the $647 million consensus. Guidance cuts are still being punished far harder than beats are being rewarded. Vistra (VST), the AI-power name, reported third-quarter results before the open — the next test of whether the data-centre spending scare has further to run.
What the positioning means
Three things stand out at midday.
First, this is a tech-led relief rally, not a broad reversal. The Nasdaq is doing the work while the Dow is flat, held back by rate-sensitive names as yields rise on the jobs data. Money is buying the dip in the trade that just got crushed; it is not yet rotating back into everything.
Second, the Nasdaq is still in correction territory. Even at 24,695.67, it sits about 10.5% below its 6 October record close of 27,599.89. Today's 1.6% bounce recovers less than a third of Thursday's 5.5% fall. The market has stopped falling; it has not yet turned.
Third, fear is easing but not gone. The VIX has fallen from Thursday's close of 26.07 to about 24.27, and gold is down 0.9% to $4,076.10 while WTI crude is at $90.18 and bitcoin is near $75,900. Investors are slightly less defensive than they were yesterday — but a VIX above 24 after a week like this one says nobody is relaxed.
What to watch next
The close matters more than the midday level. A Nasdaq that holds a 1.5% gain into the close would be the first sign of stabilisation after two violent days; a fade into the close would say the dip buyers are not yet in control. Federal Reserve speakers are scattered through the afternoon, and any comment on the December meeting will move yields and tech in opposite directions.
Beyond today, the calendar stays heavy: October CPI arrives on 10 November, and the Fed's next meeting is 8–9 December, with the market now pricing a December hike at better than three-in-four odds. The jobs report answered the growth question — hiring is strong. It sharpened the rates question instead. That tension is the story of this market right now, and it will not be settled by one morning's bounce.
For exploration only. Not financial advice.
Sources
- LSE / Financial News: US open: Nasdaq leads the recovery after Thursday's selloff
- jbiznews: Stocks Open Mixed After Blowout October Jobs Report
- World Money Roadmap: US Stocks Live Nov 6: Nasdaq +1.57% as Chip Rebound Holds
- The Edge: US Market Wrap 6 November: Early Session, the Nasdaq 100 Gains 1.57% on Chip Buying
- Invezz: Nasdaq rebounds 1% as chip stocks recover; Dow falls despite strong jobs data
- Zacks: Stock Market News for Nov 6, 2026
- Barchart: Stock Indexes Push Higher as Chipmakers Roar Back
- Finimize: Michigan Consumer Sentiment Ticked Up In November
- Finnhub: AMD, Micron, Nvidia and Cloudflare market data, November 6, 2026
- TradingKey via Mitrade: Chip Stocks Rebound as Micron, AMD Rise Over 8%
- Stock Market Watch: Premarket Movers, November 6, 2026
- 7globe: US stock market today: Nasdaq rebounds after worst sell-off, October jobs report in focus