Market News
Midday: the PPI relief rally fades — chips drag the Nasdaq 1.3% lower as the 10-year yield hits a four-week high
Wall Street opened higher on a softer-than-expected October PPI, then gave it all back. As of 12:25 ET the S&P 500 is down 0.8% and the Nasdaq 1.3%, AMD is down 10.5% as Thursday's rotation into Nvidia's rivals unwinds, and the 10-year Treasury yield has climbed to a four-week high of 5.17%.
Friday 13 November, midday: the relief rally lasted about an hour. Wall Street opened higher after October producer prices came in a touch softer than expected, then gave it all back — and then some. As of 12:25 ET, the S&P 500 is down 0.8% and the Nasdaq Composite is down 1.3%, while the Dow Jones Industrial Average is holding up better, down 0.17% at the last check, around 11:12 ET. The morning's story is the same as the week's: chips are selling off, yields are rising, and the Federal Reserve's December hike is looking more certain, not less.
The session started well. The Dow opened up 0.37% at 52,490.68, the S&P 500 up 0.32% at 7,616.85 and the Nasdaq up 0.17% at 25,408.00. By 9:38 ET the gains were already fading — the S&P 500 at 7,585.65, down 0.09%, and the Nasdaq at 25,269.40, down 0.38%. By 10:16 ET the slide was in full swing: the Dow at 52,081.40, down 0.41%, the S&P 500 at 7,519.10, down 0.93%, and the Nasdaq at 25,006.20, down 1.42%. The market has steadied a little since then, but it has not recovered.
Producer prices: softer for a month, hotter for a year
October's producer price index (PPI) rose 0.3% from September, below the 0.4% economists expected and a sharp slowdown from September's upwardly revised 1.4% jump. Core PPI, excluding food and energy, also rose 0.3%, in line with forecasts. That was enough to lift futures before the bell — and to push stocks higher at the open.
But the annual figures told a different story. Headline PPI is up 6.5% from a year earlier, the fastest pace since November 2022, and goods prices are up 10.2% over the year. Cheaper energy did the monthly work — crude oil prices fell 10.3% and diesel 7.9% in October — while core goods prices still rose 0.5%. With the CPI and PPI data in hand, economists estimate core PCE inflation, the Fed's preferred gauge, rose 0.3% in October.
Why it matters: the monthly number gave the market its morning bounce, but the yearly number is what the Fed watches. Two Fed officials made that point today: Chicago Fed President Austan Goolsbee said the Fed "has work to do" on inflation, and Boston Fed President Susan Collins said tighter policy may be needed to cool prices. Markets now price a 100% chance of a 25-basis-point hike at the December 8–9 meeting, and the 10-year Treasury yield climbed to a four-week high of 5.17%. A hike in December is no longer the question — the question is what comes after it.
Nvidia (NVDA): the bounce failed
Nvidia (NVDA) opened at $169.91, near its high of the day, and then slid all session. As of 12:38 ET it is trading at $161.39, down 2.9% on the day, after touching $158.39 at its low. The premarket rebound — about 2% higher before the bell — is gone. The stock is down 7.3% since Wednesday's close, on track for a sixth straight weekly loss, its longest such streak since October 2012, and it has now given up close to $1.4 trillion in market value since its October 6 record.
Why it matters: Thursday's 4.3% drop was a governance story — chief executive Jensen Huang resigned and chief financial officer Colette Kress was named interim chief executive. Today's slide is a market story: the whole chip complex is falling with it, and the bounce buyers who stepped in before the open have been run over. Nvidia reports third-quarter results on Tuesday 17 November, its first under the new leadership, and that report is now the week's main event.
The rotation into Nvidia's rivals is unwinding
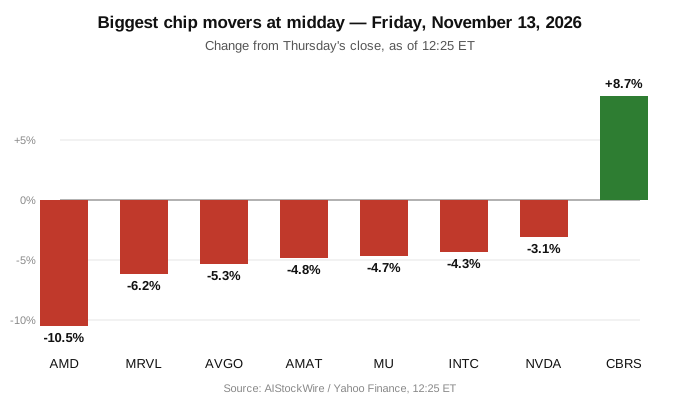
Thursday's winners are today's biggest losers. Advanced Micro Devices (AMD) is down 10.5% at $524.09 as of 12:25 ET, giving back all of Thursday's 5.9% gain and then some — it now sits 5.2% below Wednesday's close. Broadcom (AVGO) is down 5.3% at $344.90, erasing Thursday's 5.5% rise and returning to roughly where it started the week. The Philadelphia Semiconductor Index is down 4.5%.
The selling runs through the whole group: Marvell (MRVL) is down 6.2%, Arm (ARM) 5.4%, Applied Materials (AMAT) 4.8%, Micron (MU) 4.7%, Intel (INTC) 4.3% and TSMC (TSM) 2.5%. The AI cloud names are falling harder still: CoreWeave (CRWV) is down 8.1% at $52.00 and Nebius (NBIS) is down 10% at $115.80, now 25.1% below Wednesday's close after falling 16.8% on Thursday.
Why it matters: this is no longer a single-stock story. When the supposed beneficiaries of Nvidia's troubles fall further than Nvidia itself, the market is repricing the whole AI trade — slower spending, higher rates, and a flood of new equity supply, with Anthropic's IPO next week reportedly about six times oversubscribed. The question for the afternoon is whether the selling stays in chips or spreads wider: so far the Dow's resilience says it is still contained.
The exceptions: Cerebras (CBRS) and Modine (MOD)
Not everything in AI hardware is falling. Cerebras (CBRS) is up 8.7% at $106.26 as of 12:25 ET after reporting a surprise adjusted profit, raising its full-year revenue forecast to $940 million to $960 million, and signing Microsoft (MSFT) as a cloud customer. It was the morning's biggest premarket gainer and it has held most of the move. Modine (MOD) is up more than 28% on reports that Samsung Electronics is in talks to acquire the data-centre cooling maker.
Why it matters: the market is still rewarding real numbers. Cerebras showed revenue growth and a raised outlook; Modine has a takeover bid. In a tape where good earnings are being sold — see Cisco below — a genuine beat with a genuine customer is one of the few things still working.
Cisco (CSCO): a beat the market sold anyway
Cisco (CSCO) is down more than 5%, the biggest loser in the Dow, despite beating expectations and raising its outlook. Fiscal first-quarter revenue was $18.5 billion, up 24% year over year, with adjusted earnings of $1.40 a share against the $1.33 expected. But product orders grew 21%, below expectations and a slowdown from the previous quarter, and that was enough. The shares had already risen on Thursday and fell 2.9% premarket.
Why it matters: Cisco is the day's cleanest example of a market that is not in a forgiving mood. A 24% revenue gain and a raised forecast used to be enough for a rally; today it is a 5% decline. When beats get sold, the bar for next week's earnings gets higher — Nvidia reports on Tuesday, Home Depot and Disney the same day, and Target and Lowe's on Wednesday.
Rates, crypto and oil
Bitcoin is down more than 4% to a two-and-a-half-month low, below $70,000 — it traded at $69,155 premarket. Crude oil turned higher during the morning even after the International Energy Agency cut its 2026 demand forecast to 102.29 million barrels a day and said global markets will swing to a surplus of 2 million barrels a day this quarter. The lift came from the Middle East: US Central Command said it shot down two attack drones launched by Iran's IRGC toward a US base in Bahrain.
On the earnings front, the broader picture is still strong: third-quarter S&P 500 earnings are expected to climb 31% from a year earlier, according to Bloomberg Intelligence, with 451 companies having reported and 84% beating estimates. That is the tension in this market — earnings are growing fast, but rates and leadership turmoil are setting the price investors will pay for them.
What to watch into the close
- Whether the Dow's resilience holds, or the selling spreads from chips into the broader market.
- Fed officials Michelle Bowman and Philip Jefferson speak today.
- Nvidia's results on Tuesday 17 November, and the retail earnings that follow — Home Depot and Disney on Tuesday, Target and Lowe's on Wednesday.
- The 10-year yield: above 5.17% it keeps pressure on growth stocks; a retreat would ease it.
For education only. Not financial advice.
Sources
- Reuters via TNN: Stock Market Today Nov. 13, 2026 — S&P 500, Nasdaq Fall as Nvidia Slides
- Barchart: Stocks Retreat as Chipmakers Sink and Bond Yields Rise
- AIStockWire: AMD, Broadcom erase post-Huang rally as chips slide
- Finnhub: NVIDIA Corporation (NVDA) market data
- Reuters via 935 The Lloyd: US producer prices rise moderately in October, but inflation broadens out
- Zacks: PPI +6.5% YoY — Highest in Nearly 4 Years
- MLQ.ai: Wall Street opens mixed as Nvidia reverses lower and Cerebras jumps 15% after a cooler PPI
- Bank of Vol: Nvidia Steadies, Microsoft Goes Dark, PPI at 14:30
- Regards of Wall Street: Stock Market Futures Today — S&P 500 Futures Up 0.30% Before the Open, Nov 13