Market News
Midday: Nvidia's $115.8 billion beat fades into a fifth straight down day, retail surges, and UnitedHealth drags the Dow toward 50,000
As of 12:10 ET the S&P 500 is down 0.34% at 7,315.50 and the Dow down 0.97%, with Nvidia reversing a 3.14% premarket gain into a loss. TJX jumps 10.4% and Target 5.6% on strong retail results, UnitedHealth plunges, and the Fed minutes land at 2:00 p.m. ET.
Wednesday 18 November, midday: the relief rally did not survive the morning. Nvidia reported revenue of $115.84 billion, up 103% from a year earlier, and guided the current quarter to about $130 billion — the beat the market had waited for. Nasdaq 100 futures rose 0.86% before the open, and Nvidia's shares were up 3.14% premarket at $160.34. By midday the gain had reversed entirely: the shares were down about 2.5% by 11:48 ET, and the market was heading for a fifth straight losing session. As of 12:10 ET, the S&P 500 is down 0.34% at 7,315.50, the Nasdaq Composite is flat at 24,339.18, up 0.04%, and the Dow Jones Industrial Average is down 0.97% at 50,266.43.
The fade began early and ran through the morning. About 84 minutes into the session the S&P 500 was already down 0.43% at 7,308.94 and the Dow down 1.24% at 50,128.62, while the Nasdaq held near flat at 24,336.18 and the small-cap Russell 2000 rose 0.48% to 2,714.72. By 11:32 ET the S&P 500 was down 0.48% at 7,305 and the Dow down 1.17% at 50,167. Tuesday was the fourth straight losing session: the Dow fell 848.75 points, or 1.64%, to 50,759.42; the S&P 500 fell 1.03% to 7,340.53, its lowest close since 29 July; and the Nasdaq dropped 0.74% to 24,328.38. The Nasdaq is now in correction territory, more than 10% below its 6 October high.
Nvidia (NVDA): the beat that was not enough
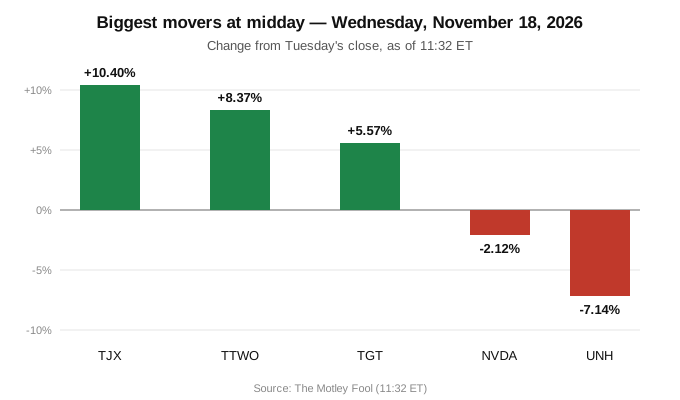
Nvidia's numbers were strong across the board. Revenue was $115.84 billion, up 103% from a year earlier and ahead of the roughly $109 billion analysts expected. Adjusted earnings were $2.68 a share against $2.47 expected, data centre revenue rose 110% to $107.6 billion, and the company forecast about $130 billion for the current quarter, above the roughly $125 billion expected. It also added $150 billion to its share buyback. The shares opened higher and then turned: they were at $160.34 premarket, up 3.14% from Tuesday's close of $155.46, and by midday they were trading about 2.1% lower.
Why it matters: this was the most important earnings report of the season, and the market's answer so far is that even a doubling of revenue is not enough. When a company beats on the quarter and the outlook and still falls, the message is that the growth was already in the price — and that leaves the most richly valued stocks with little room for error. The morning's chip rally faded with it: the gains in the wider chip complex that followed the report in premarket trading did not hold into the session.
Retail surges: TJX and Target reward the consumer
Retail provided the day's bright spot. The TJX Companies (TJX) surged 10.40% and Target (TGT) climbed 5.57% after encouraging quarterly results and raised full-year guidance. Lowe's was the exception among the three retailers that reported this morning: it fell 4.29% premarket after cutting its operating margin outlook, even though its earnings beat included a $0.34 tariff refund.
Why it matters: two beats that the market is actually rewarding is a change from recent sessions, where good numbers were sold anyway. The results offer some reassurance about consumer spending heading into the holiday shopping season, and investors get the next big read on Thursday, when Walmart (WMT) reports before the open. The split verdict also fits the morning's pattern: the market is grading companies on what comes next, not on the quarter just reported — Target beat and raised its outlook and rose, Lowe's beat and cut its margin outlook and fell.
UnitedHealth (UNH) drags the Dow toward 50,000
The Dow is the weakest of the three major indexes, and one stock is doing much of the damage. UnitedHealth Group (UNH) plunged 7.14% at midday, extending its recent losses as investors grow more concerned about rising medical costs and pressure on profit margins. Healthcare weakness, together with selling in software stocks, pushed the Dow to 50,167 by 11:32 ET, closer to the psychologically important 50,000 level.
Why it matters: the Dow's slide is not a broad economic verdict — it is concentrated in a handful of heavyweights, and UnitedHealth is the largest drag today. But a Dow flirting with 50,000 after closing at 50,759 on Tuesday tells the same story as the rest of the session: buyers are not stepping in to defend levels that held only days ago. Take-Two Interactive (TTWO) went the other way, jumping 8.37% on positive reception for Grand Theft Auto VI, which launches tomorrow.
Housing starts beat, but permits point the other way
The morning's economic data was mixed. October housing starts rose 9.9% to a 1.309 million annual pace, beating the 1.245 million forecast and ending a three-month decline. Single-family starts rose 4% to 864,000, while apartment and condo starts jumped 25.5% to 433,000. But building permits — the better guide to future construction — fell 7.4% to 1.295 million, and permits for single-family homes tumbled 8.7% to 772,000, the lowest since January 2023. The 30-year mortgage rate averaged about 7.11% last week, and homebuilder sentiment has fallen to its lowest in more than 14 years. The Census Bureau also notes a margin of error of plus or minus 16.8 points on the monthly change, so the rise in starts is not statistically significant.
Why it matters: the housing market is still caught between a small rebound in building and a pipeline that is shrinking. Starts that beat the forecast sound encouraging, but permits at a three-and-a-half-year low say builders do not expect demand to follow. With mortgage rates above 7%, the housing data is unlikely to change the Federal Reserve's thinking — which brings the afternoon into focus.
The cross-asset picture: gold slides, yields ease, Bitcoin falls
Selling pressure extended beyond equities. Gold tumbled 3.10% to $3,744.30 an ounce at midday, below $3,800 for the first time and at a one-year low — it was already down 2.38% premarket at $3,772.30. The 10-year Treasury yield eased to 5.06%, down 5 basis points, but remains near recent highs above 5%. The dollar index stood near 103.9, up 0.37%, close to a 19-month high. Bitcoin fell 3.45% to $62,652, dropping with equities rather than acting as a refuge. The VIX, the market's fear gauge, was at 25.6. Industrial and consumer discretionary stocks provided some pockets of strength, while communication services lagged.
Why it matters: gold falling while stocks fall breaks the usual safety-trade pattern — when the traditional refuge slides too, it points to investors raising cash rather than rotating into safety. A 10-year yield above 5% keeps borrowing costs high for households and companies alike, and it is the backdrop against which every earnings beat is being judged.
What to watch into the close
- The minutes of the Federal Reserve's October meeting, due at 2:00 p.m. ET. The Fed held its benchmark rate at 3.75% to 4% at that meeting, and the market prices a 95.4% chance of a quarter-point rate hike in December. With the 10-year yield above 5%, investors will read the minutes for any sign the Fed is leaning toward that hike.
- A 20-year bond auction at 1:00 p.m. ET — the last one sold at 5.469% — with Fed official Barr speaking at 1:35 p.m. and New York Fed President Williams at 2:30 p.m.
- Palo Alto Networks (PANW) reports fiscal first-quarter results after the close.
- Walmart (WMT) reports before the open on Thursday, the next big read on consumer spending heading into the holiday season.
- The Dow's 50,000 level: a close below it would leave the average at its weakest point of a five-day slide heading into the Fed minutes.
For education only. Not financial advice.
Sources
- The Motley Fool: Stock Market Midday, Nov. 18: Nvidia Doubles Revenue, but Wall Street's Sell-Off Continues
- Pulsafi: Today's Market Pulse — November 18, 2026
- CAMS: Midday Market Check: November 18, 2026
- The Edge: US Market Wrap 18 November: Early Session, the Dow Falls 1.24% and the Russell 2000 Rises
- Homes.com: US housing starts rise 9.9% in October after a three-month dip
- Reuters (via WDSM): US single-family housing starts rebound in October; building permits plunge
- InvestingLive: US October housing starts 1.309M vs 1.245M expected