Market News
Midday: the chip bounce fades, software leads a fourth straight down day, and Nvidia's earnings decide the week
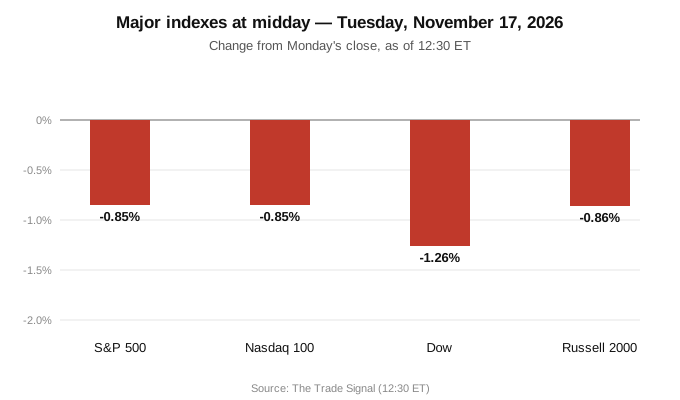
As of 12:30 ET the S&P 500 is down 0.85% at 7,353.30 and the Dow down 1.26%, with every major index below its opening range and Monday's low. Salesforce leads a broad software sell-off, the morning's chip bounce has faded, and Nvidia reports after the close.
Tuesday 17 November, midday: the bounce did not hold. Futures pointed to a modest technology rebound this morning — Nasdaq 100 futures were up 0.40% before the open — but by midday the market had turned lower again, and the selling is now broader than the chip story that started it. As of 12:30 ET, the S&P 500 is down 0.85% at 7,353.30, the Nasdaq 100 is down 0.85% at 26,964.79, the Dow Jones Industrial Average is down 1.26% at 50,960.21, and the Russell 2000 is down 0.86% at 2,719.30. All four indexes are below their opening ranges and below Monday's lows, and the Nasdaq 100 has fallen to a 6.75-month low. It is the fourth straight down day for US stocks.
The trajectory through the morning has been steadily lower. At 10:24 ET the S&P 500 was down 0.40% at 7,386.69; by 12:30 ET it was down 0.85%, having traded as low as 7,288.34. The Dow has been the weakest of the three major indexes all session, trading in a range of 50,685.51 to 51,463.53. The VIX, the market's fear gauge, is at 25.37, up 8.33% on the day after touching 27.73 intraday — it closed Monday at 22.91, itself up 18.7% on the day. Monday was the third straight losing session: the S&P 500 fell 1.92% to 7,416.59, the Nasdaq Composite dropped 2.49% to 24,509.76, putting it more than 10% below its 6 October high and in correction territory, and the Dow fell 1.41% to 51,608.17.
Software leads the slide: Salesforce (CRM) down 9.7%
The day's sharpest large-cap move is not a chip stock at all. Salesforce (CRM) is down 9.66% at $194.08 as of 12:30 ET, the biggest loser in both the S&P 500 and the Dow, and it has fallen with no company-specific news behind the drop. It is the front of a broad software sell-off: Intuit (INTU) is down more than 6%, Atlassian (TEAM) and ServiceNow (NOW) are down more than 6%, Datadog (DDOG) and Workday (WDAY) are down more than 5%, Adobe (ADBE) and Oracle (ORCL) are down more than 4%, and Microsoft (MSFT) is down 3.36% at $500.61 and IBM (IBM) more than 3%.
Three threads are weighing on the group. The first is the Anthropic initial public offering, which is due to price on Wednesday evening and start trading on Thursday — investors are asking what a large, well-funded AI rival means for established software companies, and for Microsoft in particular as OpenAI's partner. The second is a data-breach report naming Salesforce among the companies affected by malicious code from website optimisation platform Optimizely. The third is slower-moving: doubts about how fast Salesforce can turn its Agentforce AI platform into revenue, and channel checks suggesting enterprise buyers are stretching out software purchases.
Why it matters: Monday's sell-off was a chip story; today's is wider. When software — the part of the market that was supposed to benefit from cheaper AI — falls harder than the chipmakers, the market is questioning the whole AI trade, not just one company's earnings. The Dow's 1.26% drop, the worst of the three major indexes, is partly a Salesforce story: CRM is a Dow component, and its near-10% fall is dragging the average down with it.
Nvidia (NVDA): down 1.34% into the report that decides the week
Nvidia (NVDA) is trading at $154.05 as of 12:30 ET, down 1.34% from Monday's close of $156.14, and it is the most active stock in the market with 186.36 million shares traded. It opened at $157.46 and has drifted lower through the morning, touching $150.33 at its low. The company reports fiscal third-quarter results after the close, with the numbers due at about 4:20 p.m. ET and a call at 5:00 p.m. Consensus expects revenue of about $109.1 billion and earnings of $2.47 a share. It is the first report under interim chief executive Colette Kress, after founder Jensen Huang resigned on 12 November, and the first since SemiAnalysis cut its AI accelerator spending forecasts over the weekend.
Why it matters: everything today is a warm-up for this print. The market has spent the session de-risking ahead of it — software sold off, the chip bounce faded, volatility jumped — and the numbers after the close will decide whether the Nasdaq's correction deepens or finds a floor. Watch the guidance on data-centre demand and capital spending, and any word on a permanent chief executive.
The chip bounce faded by midday
The morning's rebound in chips and optical stocks has mostly evaporated. Coherent (COHR) was up 10.90% before the open; as of 12:40 ET it is up 2.40% at $208.32. Lumentum (LITE) was up 7.86% premarket; it is now up 0.90% at $550.89. The two stocks climbed this morning on reports that the Trump administration is planning to move forward with a ban on imports of Chinese optical transceivers, which would help US makers of the components that move data inside data centres. Marvell (MRVL), which agreed in November to acquire Lumentum, is caught in the same trade. Intel (INTC) is down 2.85% at $53.89.
Why it matters: a bounce that fades before midday says dip buyers are not yet convinced. The premarket gains were built on a policy headline, not on evidence that data-centre demand is recovering, and once the open arrived the sellers came back. The test from this morning's watchlist is now answered in the negative: the gains did not survive the open.
Retail sales: the consumer is still spending — just more slowly
The morning's economic data was steady rather than alarming. October retail sales rose 0.2% from September to $748.2 billion, matching expectations after September's 0.8% jump, and were up 6.8% from a year earlier. Strip out autos and the picture is stronger: sales excluding autos rose 0.6%, ahead of the 0.4% forecast, and the control group — the measure that feeds into GDP — also rose 0.6%. The softness was concentrated in big-ticket items: auto dealer sales fell 1.6% and furniture sales fell 2.3%. The Census Bureau noted the headline gain sits inside its margin of error of plus or minus 0.4 percentage points, so it could not rule out that sales were flat. October industrial production fell 0.4%, against expectations of a 0.1% rise, and the NAHB housing market index dropped to 25 from 29, against 29 expected. Hawkish comments from St. Louis Fed President Alberto Musalem also weighed on stocks and bonds during the morning.
Why it matters: the consumer is not pulling back, but the pace of spending has cooled, and the stronger core readings reinforce expectations of another Federal Reserve rate rise at the December meeting. A resilient consumer and a hawkish Fed are an awkward combination for stocks: it keeps the economy growing while keeping rates higher for longer, and the 10-year Treasury yield, at 5.099%, is still above 5%.
The exceptions: a biotech breakout, Disney turns positive, Home Depot stays down
Not everything is falling. SELLAS Life Sciences (SLS) is the day's biggest gainer, up 174.77% at $20.53, after its experimental leukaemia vaccine met the main goal of its Phase 3 REGAL trial: a 41% reduction in the risk of death, with a hazard ratio of 0.59 and a p-value of 0.035, and median survival of 24.0 months against 14.7 months for the comparison group. The stock opened up 216% and touched $24.89 intraday. The company plans to meet with the Food and Drug Administration to discuss an accelerated filing, with a biologics licence application planned for the first half of 2027.
Walt Disney (DIS) has turned positive, up 0.81% at $119.66 as of 12:40 ET after falling 1.84% premarket, as the market digests a quarter in which parks, streaming and ESPN all beat expectations. Home Depot (HD) has not recovered: it is down 2.36% at $339.30 as of 12:40 ET, still punished for guidance that only narrowed rather than lifted, and it was downgraded by Citi to Sell and by Zelman to Underperform on Monday. Elsewhere, Tyson Foods (TSN) is up 8.7% on a beat, AECOM (ACM) is up 11.62%, Energizer (ENR) is up 10.85% and Snap (SNAP) is up 6.97%, while JD.com (JD) is down 7.3% after in-line earnings and Robinhood (HOOD) is down 5.9%.
Why it matters: earnings are being judged on what comes next, not what just happened. Disney beat and is being rewarded once the call details sink in; Home Depot beat and is still down because its outlook did not improve; SELLAS is a reminder that single-stock news can still overwhelm the market's mood entirely.
Sectors and the cross-asset picture
Materials is the only sector in the green, up 0.17%. Technology is the worst at minus 1.73%, followed by Financials at minus 1.41% and Health Care at minus 0.98%. The 10-year Treasury yield is at 5.099%, down 2.2 basis points on the day. Gold is up 0.49% at $3,873.50 an ounce, West Texas Intermediate crude is up 0.95% at $86.34 a barrel, and the dollar index is down 0.19% at 103.41. Bitcoin is down 2.00% at $63,712, falling with equities rather than acting as a refuge.
Why it matters: gold rising while stocks fall is the classic safety trade, but Bitcoin falling alongside stocks says risk appetite is fading across the board. With only one sector positive, this is a broad de-risking session, not a rotation — money is leaving equities rather than moving between them.
What to watch into the close
- Nvidia's earnings after the close, due at about 4:20 p.m. ET — the report that decides whether this is a correction or something longer.
- The minutes of the Federal Reserve's October meeting, due Wednesday at 2:00 p.m. ET, and whether the retail sales data shifts the December rate debate.
- Anthropic's initial public offering, due to price on Wednesday evening, with shares starting to trade on Thursday.
- Results from the TJX Companies (TJX), Lowe's (LOW) and Target (TGT) before the open on Wednesday, and Palo Alto Networks (PANW) after the close.
- Walmart (WMT) reports before the open on Thursday, the next big read on consumer spending heading into the holiday season.
- The 7,288 level on the S&P 500, today's low so far: a break below it into the close would leave the index at its weakest point of the session heading into Nvidia's numbers.
For education only. Not financial advice.
Sources
- The Trade Signal: Midday brief, Tuesday, November 17, 2026
- Barchart: Stock Indexes Fall as Tech Stocks Retreat Ahead of Nvidia's Earnings
- Zacks: Stock Market News for Nov 17, 2026
- Pulsafi: Today's Market Pulse, November 17, 2026
- TipRanks: Why Is Salesforce Stock (CRM) Down 9% Today?
- Morningstar: Coherent and Lumentum stocks climb as potential U.S. import ban threatens Chinese rivals
- Coinpedia: SLS Stock Soars More Than 200% After Phase 3 Cancer Vaccine Success
- AIStockWire: Sellas (SLS) stock more than doubles on Phase 3 REGAL data
- Reuters: US retail sales increase moderately; import prices rise above expectations
- FXStreet: US Retail Sales rose by 0.2% MoM in October
- MarketFlux: US October Retail Sales Beat Forecasts Across the Board, Reinforcing Case for Fed Rate Hike
- Zacks: Retail Sales Increased in Line with Expectations
- Frenzy Capital: Stock Market Analysis for Tuesday, November 17, 2026
- Finnhub: Home Depot (HD) quote
- Finnhub: Walt Disney (DIS) quote
- Finnhub: Coherent (COHR) quote
- Finnhub: Lumentum (LITE) quote