Market News
Stocks to watch today: Nvidia's earnings land after the Nasdaq's correction, chips bounce, and Home Depot and Disney beat — then slip
Nasdaq 100 futures are up about 0.4% after the Nasdaq Composite entered a correction on Monday. Nvidia reports after the close — its first results under interim chief executive Colette Kress — chip and optical stocks are bouncing, and Home Depot and Disney both beat earnings yet trade lower premarket.
Tuesday 17 November opens with the market holding its breath. Monday was the third straight losing session: the S&P 500 fell 1.92% to 7,416.59, the Nasdaq Composite dropped 2.49% to 24,509.76 — putting it more than 10% below its 6 October high, in correction territory — and the Dow Jones Industrial Average fell 1.41% to 51,608.17. The Nasdaq 100 lost 2.67% and the Russell 2000 fell 1.70%. This morning the tone is steadier but narrow. As of 07:10 ET, Nasdaq 100 futures were up 0.40% and S&P 500 futures up 0.03%, while Russell 2000 futures were down 0.42% and Dow futures down 0.32%. The split says the same thing as Monday: this is a technology story first, and everything else second. The VIX, which jumped 18.70% on Monday to 22.91, was at 22.57 as of 07:10 ET.
Nvidia (NVDA): the report the whole market is waiting for
Nvidia reports fiscal third-quarter results after the close today, with the numbers due at about 4:20 p.m. ET and a call at 5:00 p.m. It is the company's first report since founder Jensen Huang resigned as chief executive on 12 November, and its first under interim chief executive Colette Kress. Consensus expects revenue of about $109.1 billion and earnings of $2.47 a share. The stock was up 0.81% premarket to $157.40 as of 07:10 ET, a small bounce after closing Monday at $156.14, down 4.12% at a new 52-week low. The company has lost roughly $735 billion in market value since the leadership scandal broke.
Why it matters: this is the most important earnings report of the season, and the questions go beyond the quarter. Investors want to hear whether AI demand is still growing after SemiAnalysis cut its AI accelerator spending forecasts over the weekend — its 2028 estimate down 28% to $758 billion and its 2030 estimate down 40% to $923 billion. The board has been reported as not discussing bringing Huang back, and the Commerce Department moved on Monday to close a loophole that let Chinese companies rent Nvidia computing power through data centres in other countries. Watch the guidance on data-centre demand and capital spending, and any word on a permanent chief executive. The stock's Monday close of $156.14 is the line to hold into the print.
Chips and optical stocks bounce after two days of selling
The chip sell-off is pausing this morning. AMD was up 3.10% premarket, Micron (MU) up 2.14% and SanDisk (SNDK) up 1.81% as of about 07:15 ET, after AMD fell 5.6% and Micron more than 7% on Monday, when the Philadelphia Semiconductor Index dropped 5.28%. TSMC (TSM) was up 0.39%, Broadcom (AVGO) up 1.45% and Arm (ARM) up 2.49%, and the leveraged semiconductor ETF SOXL was up 5.09%.
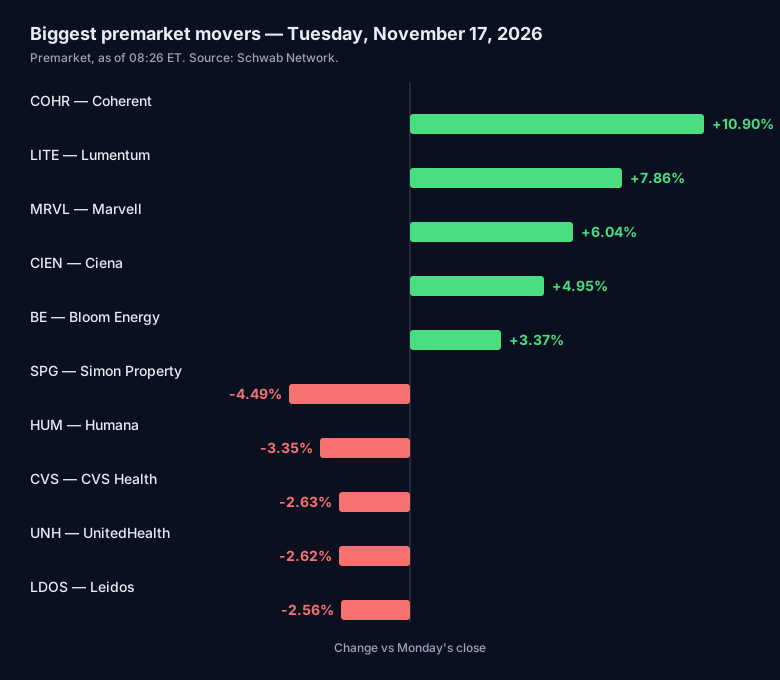
The optical names are leading the rebound. Coherent (COHR) was up 10.90% premarket, Lumentum (LITE) up 7.86%, Marvell (MRVL) up 6.04%, Ciena (CIEN) up 4.95% and Bloom Energy (BE) up 3.37%. Lumentum's move tracks Marvell: the two agreed on 2 November that Marvell would acquire Lumentum in an all-stock deal worth 4.5 Marvell shares for each Lumentum share, so Lumentum now trades largely off Marvell's price. B. Riley cut its Lumentum price target to $659 from $770 while keeping a Neutral rating, basing the target on that exchange ratio.
Why it matters: after two days in which the AI trade was sold indiscriminately, buyers are stepping back in — but selectively, into the networking and optical plumbing of data centres rather than the chipmakers themselves. Watch whether the gains survive the open: a bounce that fades before midday would say the dip buyers are not yet convinced, while a hold above Monday's lows would be the first sign the selling is exhausting itself ahead of Nvidia's numbers.
Home Depot (HD): a beat, a new chief executive — and a lower share price
Home Depot reported third-quarter revenue of $43.4 billion, up 5.0% from a year earlier and $620 million ahead of forecasts, with adjusted earnings of $3.86 a share against $3.84 expected. Comparable sales rose 2.2%, including 2.2% in the US, ahead of the 1.8% expected. Customers made 0.5% fewer trips but spent more on each one, and the operating margin slipped to 12.6% from 12.9%. For the full year the company now expects sales growth of about 4.5%, comparable sales growth of about 1.4% and adjusted earnings growth of about 2% — narrowing its previous range rather than lifting it. The company also named finance chief Richard McPhail as its next chief executive, effective 23 November, with Ted Decker remaining chair. Despite the beat, the shares were down 1.92% premarket to $340.83 as of 08:06 ET, against Monday's close of $347.51.
Why it matters: Home Depot is the morning's cleanest read on the American consumer, and the market's verdict is that a beat is not enough when the outlook only narrows. The housing-linked retailer is also the stock most exposed to the retail sales report released at 8:30 ET. Watch the 9:00 a.m. ET call for what management says about demand into the holidays, and whether the shares can climb back above $347.51 during the session.
Disney (DIS): parks, streaming and ESPN all beat — shares still fall
Walt Disney reported fiscal fourth-quarter adjusted earnings of $1.77 a share, ahead of the $1.67 analysts expected, on revenue of $25.9 billion, up 16%. Entertainment revenue rose 17% to $11.9 billion, with operating income up 92% to $1.3 billion, helped by higher streaming subscription revenue. The experiences division, home to the theme parks and cruise ships, reported record revenue and profit. Sports revenue rose 16% to $4.6 billion as ESPN viewership for the start of the NFL and college football seasons reached record highs. The company will lift cash content spending 9% to $26 billion next fiscal year, is targeting $3 billion of annual cost savings by 2029 including more job cuts, expects double-digit earnings growth next year, and raised its dividend 33%. Even so, the shares were down 1.84% premarket to $116.51 as of 08:07 ET, against Monday's close of $118.70.
Why it matters: Disney beat on every line that matters — parks, streaming, sports — and the market still sold it, because the price of that growth is a bigger content bill next year. It is the same trade as Home Depot: good numbers, cautious guidance, lower shares. Watch whether the stock turns positive once the call details are digested, and whether $118.70, Monday's close, acts as resistance during the session.
JD.com (JD): China's consumer is still cautious
JD.com missed third-quarter estimates on Tuesday, reporting revenue of 309.6 billion yuan ($46.45 billion) against the 311.48 billion yuan analysts expected, and adjusted net profit of 8.3 billion yuan against 8.59 billion yuan expected. Revenue from electronics and home appliances, its largest category, was 127.73 billion yuan, slightly above the 127.44 billion yuan expected. Cautious spending by Chinese consumers amid an economic slowdown weighed on demand. China's own October retail sales rose just 0.4% from a year earlier, below the 0.8% economists expected.
Why it matters: JD.com is the morning's second consumer read, and it points the other way from Home Depot's beat — the Chinese consumer is still pulling back. Watch whether the miss drags other US-listed Chinese names lower at the open, and whether JD.com finds buyers after the initial reaction.
The rest of the morning's movers
Health care is the soft spot outside technology. Simon Property Group (SPG) was down 4.49% premarket, Humana (HUM) down 3.35%, CVS Health (CVS) down 2.63%, UnitedHealth (UNH) down 2.62% and Leidos (LDOS) down 2.56%. Solventum (SOLV) was the morning's steepest faller, down about 25% premarket. Cisco (CSCO) drew two upgrades to Buy, from DZ Bank and HSBC. Klarna (KLAR) and Viking Holdings (VIK) also report before the open.
What else to watch today
October retail sales were released at 8:30 ET, with economists expecting a 0.1% rise after September's 0.8% jump to $745.0 billion; sales excluding autos were forecast up 0.4%, and the control group — the measure that feeds into GDP — also up 0.4%. The market's reaction will be visible in the first hour. Industrial production follows at 9:15 ET and the NAHB housing market index at 10:00 ET, and Federal Reserve Governor Christopher Waller speaks at 9:10 a.m. ET.
Tomorrow brings the minutes of the Federal Reserve's October meeting at 2:00 p.m. ET, along with results from the TJX Companies (TJX), Lowe's (LOW) and Target (TGT) before the open and Palo Alto Networks (PANW) after the close. Anthropic's initial public offering is due on Wednesday, and Walmart reports before the open on Thursday. President Donald Trump arrived in the Philippines on Tuesday for the ASEAN summit before the APEC forum in China, where a summit with Xi Jinping is scheduled in Shenzhen.
Elsewhere, West Texas Intermediate crude was up 0.76% to $86.35 a barrel, gold was up 0.33% to $3,865.90 an ounce, and the dollar index was up 0.04% to 103.587. Bitcoin was at $64,799 as of 07:10 ET, up 1.10%, holding above the $62,000 weekend low. The 10-year Treasury yield stood at 5.15%.
The overall picture
Monday put the Nasdaq into a correction. Today is about whether that was the washout or the start of something longer. Futures point to a modest technology bounce, not broad buying: the Nasdaq 100 is up, the Dow and the small caps are down, and two companies that beat earnings are trading lower anyway. Everything funnels into one event — Nvidia's numbers after the close. Until then, the market is marking time, and the first hour will show whether dip buyers or sellers set the tone for the rest of the week.
For education only. Not financial advice.
Sources
- Schwab Network: U.S. Stock Futures Mixed: Trump in Asia, Nvidia Earnings After Bell
- The Tapeboard: Retail Sales at 8:30 AM ET sets the tone, Tuesday, November 17, 2026
- Frenzy Capital: Stock Market Analysis for Tuesday, November 17, 2026
- Longbridge: US Market Preview, November 17, 2026
- The Financial Economy: Wall Street Selloff: Nasdaq Sinks 2.5%
- Eurasia Business News: Stock Market Today: Nasdaq Slides 2.5% as Nvidia Turmoil and Chip Restrictions Hit Tech
- Markets in Plain English: Nvidia drags Nasdaq down 2.5% as AI chip selloff deepens
- MarketsOnDeck: Nasdaq-100 Drops 2.67% Before Nvidia's $109 Billion Test
- Signals (Menon Lab): Evening Intel: Nasdaq Enters Correction as Nvidia-Linked Slide Hits Third Day
- Finnhub: Home Depot (HD) pre-market quote
- Finnhub: Walt Disney (DIS) pre-market quote
- Seeking Alpha: Home Depot beats top-line and bottom-line estimates; updates FY26 outlook
- MarketSpeaker: Home Depot Names McPhail CEO as Q3 Earnings Beat Forecasts
- Samuel & Co Trading: US Open Brief 17 Nov: Home Depot, Disney Beat Before Nvidia
- Reuters via 94.7 The Beast: Disney beats earnings forecasts, plans to increase content spending
- Reuters via Duke.fm: China's JD.com misses third-quarter estimates on weak consumer demand
- KuCoin: U.S. AI Hardware Stocks Rally in Pre-Market Trading, AMD Up 3.10%
- Finwire: Why is Lumentum stock rallying today?
- TipRanks: U.S. October Retail Sales Growth Set to Cool to 0.1% as Fed Rate Hike Bets Mount
- Musaffa: Daily US Market News, November 17, 2026
- MLQ: China's October retail sales, factory output and investment all miss forecasts