Market News
Stocks to watch today: CPI day — futures flat after Monday's best session since April, Take-Two and Sanmina surge
Futures are little changed after Monday's sharp rally — the S&P 500 jumped 2.35% in its best day since April — with all eyes on the October CPI report at 08:30 ET. Take-Two rises on GTA VI pre-orders, Sanmina surges on an AI-driven earnings beat, and Rocket Lab slides as its Neutron rocket slips to 2027.
Tuesday 10 November opens with the market catching its breath after a powerful rebound. On Monday the S&P 500 jumped 2.35% to 7,549.94, the Nasdaq Composite climbed 2.74% to 25,253.14 and the Dow added 1,104 points, or 2.15%, to 52,389.75 — the best day for stocks since April, driven by a chip rebound and falling oil prices.
This morning the mood is far calmer. As of about 08:18 ET, S&P 500 futures were at 7,576, up just 0.02%; Nasdaq 100 futures were at 27,901, down 0.40%; Dow futures were at 52,693, up 0.37%; and Russell 2000 futures were little changed. The market is waiting for one number: the October Consumer Price Index, due at 08:30 ET.
The CPI report: the day's verdict
Economists expect headline CPI to rise 0.3% month over month in October, slowing from September's 0.6% increase, with core CPI — which strips out food and energy — up 0.2%, against 0.3% the month before. There will be no year-over-year figure in the report: last year's government shutdown stopped the Bureau of Labor Statistics collecting price data last October, so no comparable index exists. Bank of America estimates the annual rates would be about 3.8% for headline and 2.7% for core, each 0.1 percentage points above September and well above the Federal Reserve's 2% goal.
Why it matters: this is the last inflation report before the Fed's final meeting of the year on 8–9 December, and markets price an 82.2% chance of a rate hike in December, according to the CME FedWatch tool. Fed Governor Christopher Waller said on Tuesday that he supports a December hike and would back a 50-basis-point increase if inflation keeps accelerating. A print in line with the 0.3% consensus would keep that hike on track; a hotter number could put the half-point move firmly on the table, while a soft 0.1% reading would reopen the debate. The 10-year Treasury yield was near 4.89% premarket, and the 2-year yield was about 4.62%.
Nvidia (NVDA): steadying after Monday's slide
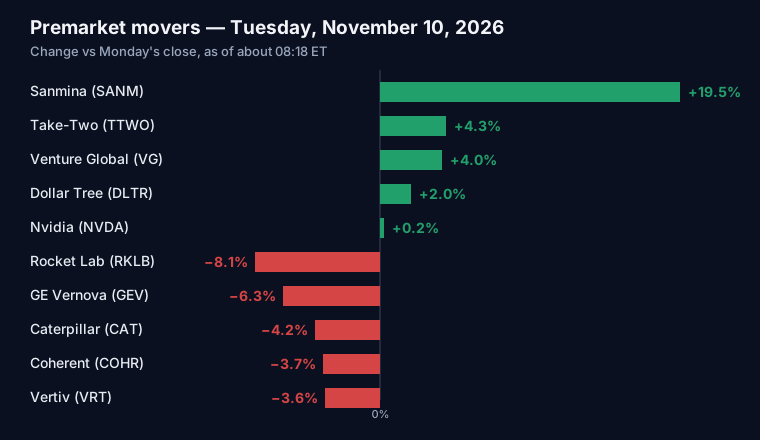
Nvidia was up modestly premarket, around $179.07 at about 06:48 ET, after falling 4.3% on Monday. The board's investigation into chief executive Jensen Huang — over reports of his links to a businesswoman US intelligence agencies allege is a Chinese spy — still hangs over the stock, and a securities-fraud class action against the company and Huang was also reported on Tuesday. The allegations have not been independently verified.
Why it matters: Nvidia fell on Monday even as the rest of the chip sector rallied, so today's small bounce is a test of whether the selling has run its course or is only pausing. Watch whether the shares hold above $179 and whether the rest of the chip complex follows — TSMC was up 1.19% premarket, while Intel fell 1.20% and AMD slipped 0.57%. Nvidia reports third-quarter results on 17 November.
Take-Two (TTWO): GTA VI carries the morning
Take-Two was the strongest large-cap gainer premarket, up 4.28% to about $216. The video game publisher reported second-quarter bookings of $1.60 billion, slightly ahead of the $1.58 billion consensus, and adjusted earnings of 99 cents per share, beating the 94-cent estimate. Revenue of $1.50 billion missed the $1.64 billion consensus, and the GAAP loss of $0.29 per share was wider than expected, but the market looked past that: Grand Theft Auto VI is confirmed for release on 19 November, just nine days away, with pre-orders continuing at what chief executive Strauss Zelnick called unprecedented levels. The company reiterated its fiscal 2027 net bookings outlook of $8.0 billion to $8.2 billion.
Why it matters: GTA VI is the most anticipated game launch in years, and the next quarter's bookings guidance of $3.35 billion to $3.50 billion is built almost entirely around it. Watch whether the shares can hold above $216 into the open — the stock is still well below its 52-week high of $265.94.
Sanmina (SANM): the AI hardware beat of the day
Sanmina surged about 19.5% premarket to around $179.65 after a thumping fourth-quarter beat. Revenue jumped 84% year over year to $3.86 billion, ahead of the $3.48 billion consensus, and non-GAAP earnings came in at $4.43 per share, up 165% and well above the $3.27 expected. Cloud and AI infrastructure revenue soared 179% to $2.37 billion, helped by the ZT Systems business, and the company guided fiscal 2027 revenue to $17.5 billion to $19.5 billion.
Why it matters: after a week in which investors questioned whether the AI data-centre buildout is slowing, Sanmina's numbers are the strongest counter-evidence of the morning — real orders, real revenue growth, and a raised outlook. Watch whether the gain lifts other AI hardware and contract-manufacturing names, or whether traders treat it as a one-stock story.
Rocket Lab (RKLB): record revenue, delayed rocket
Rocket Lab fell about 8% premarket to around $54.10, after rising almost 11% on Monday to close at $58.86. Third-quarter revenue hit a record $267.8 million, up 73% year over year and ahead of the $257.2 million consensus, and the order backlog reached a record $3.57 billion, up 52% from the second quarter. But the adjusted loss of $0.12 per share was wider than the $0.07 expected, and the first launch of the company's larger Neutron rocket has slipped into 2027 after defects were found in a propellant-tank dome.
Why it matters: the quarter shows demand is not the problem — backlog is growing fast — but the Neutron delay pushes the company's biggest growth catalyst a year further out. Watch whether the shares find support near $54, the level they traded at before Monday's jump.
Morning earnings: Sea, TransDigm and Venture Global
Three more sizeable reports landed before the bell. Sea Limited (SE) reported third-quarter revenue of $8.6 billion, up 43.4% year over year, with net income of $502.5 million, up 34%, and adjusted EBITDA of $931.3 million. Shopee, its e-commerce arm, grew revenue 41.3% and delivered a record quarter, and the board added a further $1.0 billion to the share buyback programme.
TransDigm (TDG) reported fiscal fourth-quarter sales of $2.99 billion, up 23% year over year, with earnings per share of $10.33, up 33%, and adjusted earnings per share of $12.44, up 15%. Net income slipped 4% to $586 million on higher interest and tax costs. Full-year sales rose 20% to $10.56 billion. Management hosts a call at 10:00 ET.
Venture Global (VG) reported third-quarter revenue of $4.8 billion, up 43% year over year, and net income of $2.5 billion, up 493%, as its Plaquemines LNG plant began commercial operations on 31 October. The company raised full-year adjusted EBITDA guidance to $10.0 billion to $10.3 billion, from $8.7 billion to $9.1 billion. The shares were up about 4% premarket to $12.29.
The decliners: industrials give back, crypto cools
Not everything is rising. GE Vernova (GEV) fell 6.31% premarket, Caterpillar (CAT) dropped 4.15%, Coherent (COHR) slid 3.70% and Vertiv (VRT) lost 3.63% — a cluster of industrial and AI-power names giving back some of Monday's gains. Cryptocurrency-linked stocks were lower too, with MARA Holdings down 1.81%, Coinbase down 1.01% and MicroStrategy down 1.11%, as bitcoin traded near $74,330. On the brighter side, Dollar Tree (DLTR) rose 2.01%, FedEx (FDX) gained 1.64% and Morgan Stanley (MS) added 1.97%.
Oil kept falling: WTI crude was down about 2.2% to $84.93 a barrel, with Brent down 1.35% to $91.32, after President Trump signalled the Iran conflict could end "fairly soon". Gold futures eased 0.68% to $4,085.80 an ounce, and the VIX was near 20.03.
Earnings after the close: CoreWeave headlines
The reporting day continues after the bell. CoreWeave (CRWV) is the main event — analysts expect a loss of more than $1 per share on revenue of about $3.5 billion, and the shares were up 1.25% premarket. Petrobras (PBR), Rigetti Computing (RGTI), D-Wave Quantum (QBTS) and Sonos (SONO) also report after the close. On the analyst front, DZ Bank upgraded Cloudflare (NET) from Sell to Buy, Jefferies upgraded Riot Platforms (RIOT) from Hold to Buy, and Bank of America cut Wix.com (WIX) from Buy to Underperform.
The overall picture
Monday's rally repaired some of last week's damage, but today is a waiting game. Futures are flat, the CPI print at 08:30 ET will set the tone, and the Fed's December decision now hinges on it. The earnings flow is genuinely strong — Sanmina, Sea, TransDigm and Venture Global all delivered — yet the market's biggest AI name is still working through a governance cloud, and the industrial decliners show that not every corner of the rally is holding.
The calendar after the CPI: the NFIB small-business survey is already out, Dallas Fed President Logan speaks at 10:50 ET, a $42 billion 10-year note auction is at 13:00 ET, and Fed officials Schmid and Bowman speak later in the day. Tomorrow is Veterans Day — the bond market is closed, but US stock markets are open as usual.
For education only. Not financial advice.
Sources
- Schwab Network: U.S. Stock Futures Mixed Ahead of CPI
- TipRanks: Stock Market Today, Nov. 10 — Markets Await the Consumer Inflation Report
- Regards of Wall Street: Stock Market Futures Today, Nov 10
- TradingView / Benzinga: Stock Market Today — Dow, S&P 500 Futures Rise, Nasdaq 100 Futures Fall
- StockMarketWatch: Premarket Movers
- KuCoin News: U.S. Pre-Market Mixed — NVDA and TSM Rise 1.2%, Crypto and Optical Communication Stocks Decline
- KuCoin News: U.S. stock futures show mixed movement ahead of CPI data, as Fed official signals possible 50-basis-point rate hike
- TradingView / Benzinga: Take-Two Stock Climbs on Q3 Results, 'GTA 6' Update
- Zacks: SANM Q4 Earnings Beat Estimates on AI Growth, Strong Execution
- TradingView / Benzinga: Sanmina Surges 20% After-Hours as Q4 Earnings Beat Estimates
- MarketBeat: Rocket Lab Posts Quarterly Earnings Results, Misses Expectations By $0.05 EPS
- Tulsian AI: Rocket Lab Q3 Loss $0.12, Revenue $268M
- Quantisnow: Sea Limited Reports Third Quarter 2026 Results
- PR Newswire: TransDigm Group Reports Fiscal 2026 Fourth Quarter and Year-End Results
- Quiver Quantitative: Venture Global Posts $4.8 Billion Q3 Revenue as Net Income Reaches $2.5 Billion
- Calculated Degens: Oil's slide powered the best day since April
- Simon Hertz: Nasdaq Futures Dip as Oil Slides; October CPI at 8:30 — Desk Notes for Tuesday
- The Bull Post: Here's why last year's government shutdown will haunt October's inflation data
- Binance News: October CPI Seen Up 0.3%, Keeping Fed on Course for December Rate Increase
- FI Handbook: Earnings Calendar — Week of Nov 9, 2026