Market News
Stocks to watch today: futures rebound as CoreWeave calms AI fears and Nvidia steadies after a $430 billion slide
Futures point higher after Tuesday's hot CPI sell-off — Nasdaq 100 futures up about 1.9% as CoreWeave's earnings beat calms AI-spending fears, Nvidia steadies after losing about $430 billion in two sessions, and Intel jumps on a JPMorgan upgrade and a Tesla foundry deal. The bond market is closed for Veterans Day.
Wednesday 11 November opens with a sharp change of mood. Tuesday's session ended in the red after a hotter-than-expected inflation report: the Dow fell 0.30% to 52,231.89, the S&P 500 slipped 0.38% to 7,520.93 and the Nasdaq Composite dropped 0.74% to 25,065.87. This morning the buyers are back. As of about 06:39 ET, Dow E-minis were up 58 points, or 0.11%; S&P 500 E-minis were up 65 points, or 0.86%; and Nasdaq 100 E-minis had added 527.5 points, or 1.9%. The SPDR S&P 500 ETF was up 0.69% premarket at $755.13, the Invesco QQQ Trust was up 1.57% at $685.35 and the SPDR Dow Jones Industrial Average ETF was up 0.10% at $522.25.
One quirk of the day: it is Veterans Day, so the US bond market is closed while the stock market trades a full session. Treasury yields are frozen where Tuesday left them, with the 10-year at 4.983% after jumping 11.9 basis points.
The CPI hangover — and a December hike now seen as certain
October's Consumer Price Index rose 0.4% month over month, above the 0.3% economists had expected, and the hot print revived expectations of another Federal Reserve rate increase. Traders now see a hike at the Fed's December meeting as a certainty, with an 11.5% chance of a half-percentage-point increase, according to the CME FedWatch tool.
Why it matters: the market spent Tuesday repricing rates higher, which is exactly what hurt growth stocks. Today's rebound is happening even with that repricing in place — and with no Treasury trading to confirm or challenge it, because the bond market is shut for the holiday. Watch whether the futures rally survives the open without the bond market's usual signal, and whether the VIX, which has fallen below 20 to about 19.46, keeps easing.
Nvidia (NVDA): steadying after a $430 billion slide
Nvidia was up about 5.2% premarket after closing Tuesday at $168.89, down 5.47% on the day. The chipmaker has shed about $430 billion in market value over the last two sessions as concerns mounted over chief executive Jensen Huang's affair with a Chinese businesswoman alleged to be a spy for Beijing. The board opened an independent investigation on Sunday, and the FBI is examining whether Huang was targeted by a foreign intelligence operation. The Information reported on Tuesday that the relationship helped facilitate shipments of at least $7.5 billion worth of Nvidia chips to Chinese firms. The allegations have not been independently verified, and the board says it has no reason to believe company secrets were compromised. President Trump has defended Huang, while Aletheia Capital cut the stock to Hold from Buy and removed its $340 price target.
Why it matters: Nvidia is now down 10.7% since its 4 November close of $200.13 and 26.6% below its 6 October peak of $243.37. Today's bounce is the first test of whether buyers think the sell-off has gone far enough — or whether the governance cloud keeps the stock heavy. The next hard date is 17 November, when Nvidia reports third-quarter results, and House committee chairmen have asked Huang to brief them on 18 November. Watch whether the shares can hold above $175 into the open.
CoreWeave (CRWV): the earnings beat that steadied the AI trade
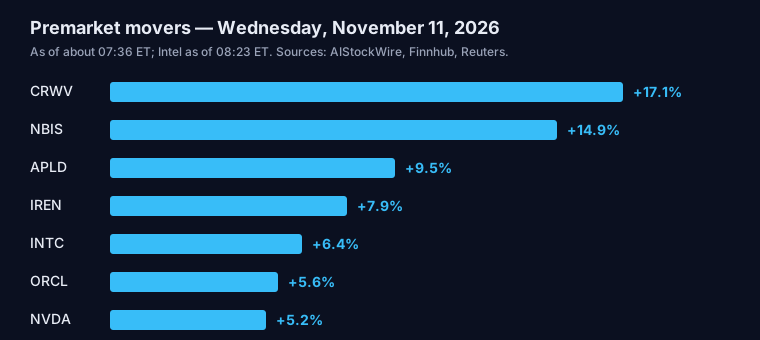
CoreWeave was the morning's biggest large-cap gainer, up 17.1% premarket to $57.08 at 07:36 ET, from Tuesday's close of $48.73. The AI cloud provider reported third-quarter revenue of $3.66 billion, up 168% year over year and ahead of the $3.55 billion analysts expected, with an adjusted loss per share of $0.95, narrower than the $1.16 expected. It raised its full-year 2026 revenue guidance to $13.0 billion to $13.3 billion, from $12.4 billion to $13.2 billion, and reported a record revenue backlog of $132.5 billion, up 138% year over year. Management said it expects to turn profitable on an adjusted basis in the first half of 2028.
Why it matters: CoreWeave is the stock investors have used as a proxy for the AI spending debate — heavy debt, heavy capital spending, and questions about whether the demand is real. The quarter answers the demand part: a $132.5 billion backlog and revenue up 168%. The financing part got an answer too: the company said it expects to collect $9 billion in customer prepayments over the next three months, and its chief financial officer said it does not plan to issue more parent-level unsecured debt through 2027 at current yields. The open questions are still the balance sheet — $46.9 billion in debt at the end of September — and capital spending, which came in at $14.5 billion for the quarter against $11.9 billion expected. Watch whether the gain holds through the session; the shares are still down about 32% this year.
Intel (INTC): the comeback name keeps running
Intel was up 6.42% premarket to $61.86 as of 08:23 ET, against Tuesday's close of $58.13. The move extends Monday's rally, when JPMorgan upgraded the chipmaker to Neutral from Underweight, with an $85 price target, and Intel disclosed that Tesla has agreed to use its forthcoming 14A manufacturing process — the first high-profile external customer for its most advanced planned node.
Why it matters: Intel is still down about 36% from its June peak — its 52-week high was $142.35 on 30 June — so today's move is a recovery within a much larger decline, not a new high. But the combination of an analyst upgrade and a marquee foundry customer is the clearest sign yet that investors are starting to price in the turnaround. Watch whether the shares can hold above $60, and whether the strength spreads to the rest of the chip complex: Micron, AMD, Alphabet, Broadcom and Meta were all trading higher premarket, and the AI infrastructure names were moving with CoreWeave — Nebius up 14.9% ahead of its earnings on Thursday, Applied Digital up 9.5%, IREN up 7.9% and Oracle up 5.6%.
After the close: Rigetti, RUM and the fertiliser names
The earnings flow continues after the bell. Rigetti Computing (RGTI) and RUM Group report, along with Mosaic, Corteva and Brighthouse Financial. With CoreWeave lifting the whole AI infrastructure group this morning, Rigetti's numbers will be read as the next check on whether the spending boom is reaching smaller names too.
Oil is firmer this morning: Brent crude was up 0.78% at $92.20 a barrel and West Texas Intermediate up 0.57% at $86.53 as of 04:30 ET. The MBA mortgage applications index was due at 07:00 ET, and there are no Bureau of Labor Statistics releases scheduled today.
The overall picture
Tuesday was a rates scare: hot inflation, a jump in yields toward 5%, and a tech-led sell-off. Wednesday is the market's answer — futures higher, led by the Nasdaq, on the back of a genuine earnings beat from CoreWeave and a steadier Nvidia. The two forces are still pulling in opposite directions: AI demand looks real in the numbers, but the cost of money is rising and the Fed is now expected to hike in December. With the bond market closed for Veterans Day, today's session will price that tension without its usual referee, so the open matters more than usual — and the first hour will show whether this is a durable rebound or a relief rally inside a rates-driven downtrend.
For education only. Not financial advice.
Sources
- Reuters: S&P 500, Nasdaq futures rise as CoreWeave results calm AI jitters
- TradingView / Stocktwits: S&P 500, Nasdaq Futures Rise Premarket — CRWV, GPRO, SPCX, NVDA, NLST Stocks In Focus
- TradingView / Benzinga: Stock Market Today — Dow, S&P 500 Futures Rise as Bessent Urges US-China to 'De-Risk'
- Upstox: Dow Jones, S&P 500, Nasdaq futures hint positive opening on Nov 11; CoreWeave, tech stocks in focus
- Longbridge: US Stock Preview — Major Index Futures Rise in Unison
- Morningstar / Dow Jones: CoreWeave's stock pops as new financing playbook eases debt concerns
- Cointelegraph: CoreWeave Stock Jumps 15% After Q3 Revenue Beats Estimates
- AIStockWire: CoreWeave (CRWV) jumps 17% premarket after Q3 beat
- Business Day: FBI investigates Nvidia CEO Jensen Huang's ties to alleged Chinese spy
- Vantage Markets: Why Is Nvidia Stock Down? 11% Slide and a Huang Spy Probe
- Motley Fool: Is Nvidia Stock a Buy on the Spy Allegation Sell-Off?
- Finnhub: Intel Corp (INTC) pre-market quote
- Finviz: Intel Shares Rise Nearly 4% Following JPMorgan Upgrade and Tesla Foundry Agreement
- DataForge Studio: Morning Market Brief — Wednesday November 11 2026
- InvestingLive: Heads up — US bond market closed for Veterans Day as stocks face a hot CPI hangover
- Fast Company: Veterans Day 2026 open and closed