Market News
Midday: stocks stage a broad rebound after the worst week since April — but Nvidia stays in the red
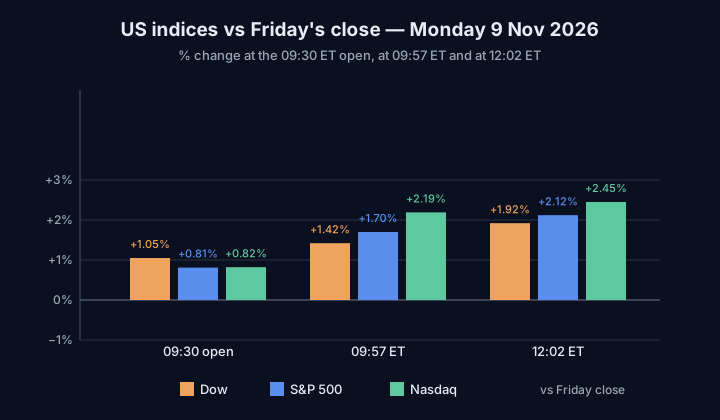
By midday the S&P 500 is up 2.1% and the Nasdaq 2.5% as dip buyers return after the worst week since April — but Nvidia is still down about 4% on the board probe, the VIX has fallen below 21, and tomorrow's CPI report is the real test.
Monday 9 November, midday: the market is buying the dip. As of about 12:02 ET, the S&P 500 is up 2.12% at 7,533.32, the Nasdaq Composite is up 2.45% at 25,182.68, the Dow Jones Industrial Average is up 1.92% at 52,270.29, and the Russell 2000 is up about 2.70%. The rebound has strengthened through the morning rather than fading: at the open the S&P 500 was up 0.81%, by 9:57 ET it was up 1.70%, and by late morning it was past 2%. One estimate put the morning's gain at roughly $1 trillion in market value.
The starting point is last week's damage. The S&P 500 fell 2.68% last week, its worst weekly decline since April 2025, and closed Friday at 7,376.86, about 5.7% below the all-time high it set last month. The Nasdaq lost 3.37% on the week to 24,579.42, the Dow fell 0.94% to 51,285.73 and the Russell 2000 slid 2.05%. Friday offered a partial steadying — the S&P 500 rose 0.31% and the Nasdaq 1.09% after a much stronger-than-expected October jobs report (165,000 jobs added, against roughly 65,000 expected) — and Monday has turned that steadying into a rally.
Figures in this article are intraday snapshots captured in New York between the open and about 12:02 ET. The session had not closed when this was written.
The one big exception: Nvidia
The rally has one glaring exception, and it is the market's second most valuable company. Nvidia (NVDA) was down about 3.9% at $179.41 by midmorning, having lost about 7% early in the session, after the board announced on Sunday an independent investigation into reports that chief executive Jensen Huang was the target of a foreign intelligence operation. The board said it has no reason to believe company secrets or national security were compromised, and Huang remains chief executive. The allegations have not been independently verified.
The selling has pushed Nvidia to its most oversold reading in years: its 14-day relative strength index fell to 24.9 at the open, the lowest since 2019, before recovering to about 27 as the shares moved off their lows. The stock now trades about 17% below its 28 October close of $215.38 and 25% below its record close of $239.24 on 6 October, and is down about 4% for the year. RBC Capital Markets maintained its Outperform rating and $330 price target on Monday.
Why it matters: the rest of the market is rallying without its biggest AI name. Nvidia lagged the S&P 500 by about 6 percentage points in the morning — a gap that, if it held to the close, would be the widest since March 2025. The market is treating this as a company-specific problem, not a verdict on AI demand. Nvidia reports third-quarter results on 17 November, the next scheduled chance for management to address investors.
Chips rebound without their leader
Remarkably, the rest of the chip complex is not following Nvidia down. In Asia, TSMC jumped 6.5%, Samsung Electronics rose 2.9% and SK Hynix gained 4.7%. In the US, AMD, Broadcom and ASML were all higher in early trading. Cloudflare (NET) was up 8.84% and Arista Networks (ANET) up 8.20%, while Amazon rose 5.33% and Apple 1.89% in early trading.
Why it matters: last week's sell-off was led by the AI infrastructure names, and this morning those same names — minus Nvidia — are leading the recovery. That is the shape of a rotation within the AI trade rather than a rejection of it: investors are still buying chips and cloud, just not the one stock carrying a governance question. The contrast with the premarket, when CoreWeave, Nebius and IREN were all down 3–5%, shows how quickly the mood turned once regular trading began.
Breadth, fear and the small-cap signal
The rally is broad, but not uniform. The Russell 2000's gain of about 2.70% outpaces the S&P 500, which says small caps — the most sensitive to borrowing costs and the domestic economy — are joining in rather than being left behind. At the same time, the count of new highs versus new lows is mixed: the S&P 500 recorded 4 new 52-week highs against 2 new lows, while the Nasdaq recorded 36 new highs against 80 new lows. The indices are rising on the strength of their largest members while plenty of individual stocks are still making fresh lows.
The fear gauge tells the clearest story of the morning. The VIX, which closed Friday at 25.64, has fallen nearly 20% to 20.54. That is a sharp relief move, though it is worth remembering that the VIX sat near 16.6 just last Wednesday — the market is calmer than Friday, not calm.
Oil falls, gold rises, yields ease
Outside equities, the other big move is oil. Brent crude fell 4.2% to $94.23 a barrel and US West Texas Intermediate fell 3.9% to $87.26 after President Trump said he was unlikely to order further strikes on Iran. Cheaper oil is a tailwind for the rally: it eases inflation pressure and leaves consumers and businesses with more to spend. Gold rose 0.99% to $4,115.30 an ounce, and the 10-year Treasury yield eased 6 basis points to 4.84%.
What to watch next
The rally's real test comes tomorrow. The October Consumer Price Index is due at 08:30 ET on Tuesday 10 November, with the Producer Price Index following on Friday 13 November. A soft inflation reading would support the case that the market's worst week since April was a buying opportunity; a hot one would put the rate-hike worries that helped drive last week's sell-off straight back on the table.
Before that, the earnings calendar keeps moving. After the close today, Occidental Petroleum (OXY), Take-Two Interactive (TTWO), Rocket Lab (RKLB), Trade Desk (TTD), Hims & Hers (HIMS), AST SpaceMobile (ASTS) and Lucid (LCID) are all due to report. And Nvidia's own results on 17 November are now the most anticipated earnings date of the month — the numbers will matter, but so will anything management says about the investigation.
For ordinary investors, the midday message is a useful one to hold on to: a market can rally strongly while its biggest stock falls, and a single day's bounce does not settle a week's worth of questions. The breadth is improving, fear is falling and the dip buyers are back — but with CPI less than a day away, today is a relief rally waiting for its confirmation.
For education only. Not financial advice.
Sources
- Reuters via 985 The River: Wall St opens higher after last week's AI rout
- TradingView / PR Newswire (Equity Insider): Wall Street's Four Main Benchmarks Start the Week Higher as Inflation Data Nears
- Daily Market Report: Equities Surge, Crypto ETFs Bleed, CPI Looms
- The Edge: US Market Wrap 9 November — Early Session, the Nasdaq 100 Gains 3.26% as Oil Prices Fall
- KuCoin News: Nvidia Stock Hits 2019-Level Oversold Conditions Amid CEO Scandal
- PreMarketDaily: AI Sector Splits as Broader Market Adds $1 Trillion at the Open
- Summa Money: US stock market today — Dow, S&P 500, Nasdaq rise as investors return to AI shares; oil slides
- Morningstar / PR Newswire (Stock Preachers): Indices Hunt for Support After Steep Weekly Losses as Volatility Gauge Stays Elevated
- Quantisnow: Wall Street's Four Main Benchmarks Start the Week Higher as Inflation Data Nears
- Tech Insider: TSMC Jumps 6.5% as Nvidia Falls 6% on Huang Row
- OrbitLens 100: Stocks to watch today — Nvidia sinks on board probe while futures climb after the worst week since April